
E-Invoicing in Barbados: VAT Tax Invoice Rules
Author
Shamyudha

In June 2018 the Barbados Revenue Authority (BRA) launched TAMIS, its Tax Administration Management Information System, for business tax filing. Invoicing has not followed: e-invoicing in Barbados still rests on Value Added Tax (VAT) invoice rules.
Barbados has no general e-invoicing mandate for B2B, B2C or B2G transactions. VAT registrants must issue tax invoices to other registrants within 30 days of the supply, with the particulars set by the VAT Regulations, 1996. VAT returns are filed in TAMIS within 21 days after the end of each taxable period.
Latest news
Embeds a monitoring pages group for this blog article
{{__MONITORING_PAGES_GROUP:blog_articles_604__}}The BRA Strategic Plan for 2025/26–2027/28 identifies electronic invoicing as a technology opportunity, without establishing a rollout timetable or technical specifications. Existing VAT invoicing obligations remain applicable, including electronic-invoice requirements introduced by Act 2019-9 for qualifying online transactions.
{{__CTA:IntegrationStepsCta__}}
Is e-invoicing mandatory in Barbados?
E-invoicing is the exchange of invoices in a structured, machine-readable format. Barbados has not mandated it; VAT relies on periodic returns, not invoice clearance.
The BRA Strategic Plan 2025/26-2027/28 names electronic invoicing only as a technology opportunity, with no timetable or format. Electronic invoices are not excluded (section 73(5) applies the Electronic Transactions Act), but an emailed PDF is not a structured e-invoice.
Barbados VAT invoicing timeline"
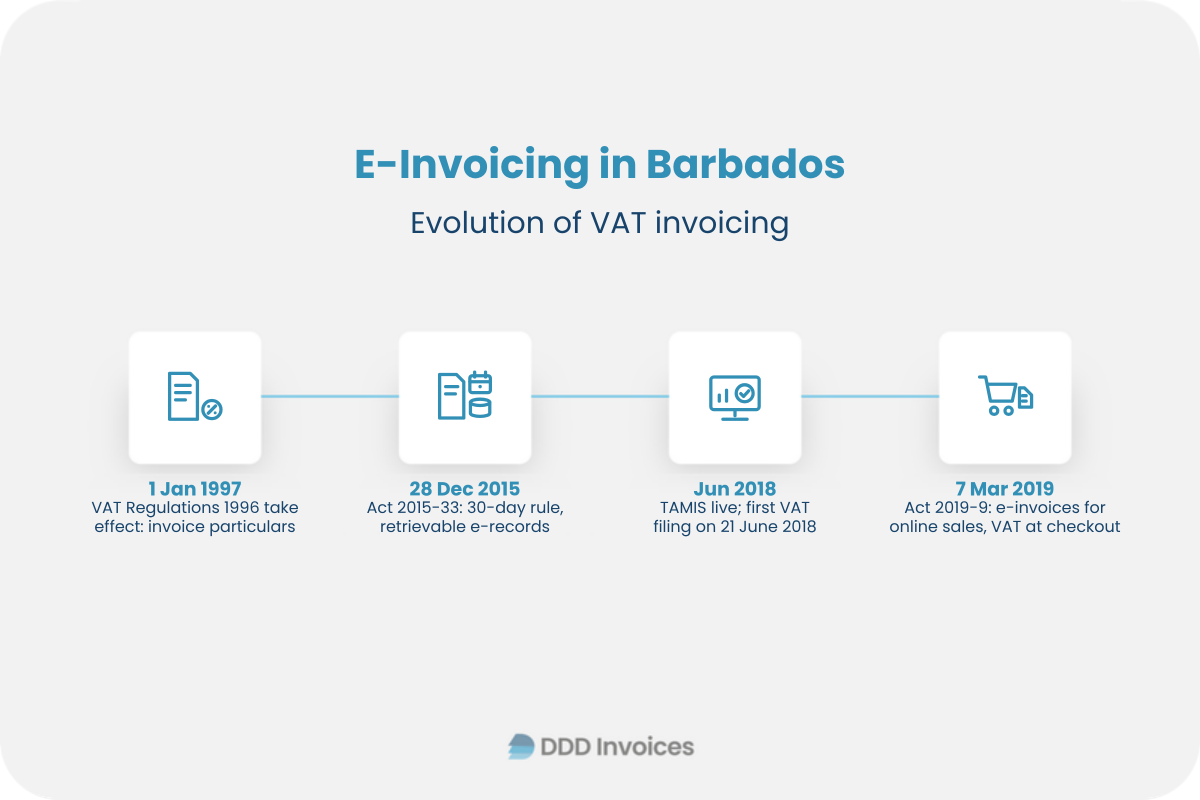
- January 1, 1997: The VAT Regulations, 1996 take effect, setting tax invoice particulars.
- December 28, 2015: Act 2015-33 adds the 30-day invoice rule and retrievable electronic records.
- June 2018: TAMIS goes live; the first VAT filing date is June 21, 2018.
- March 7, 2019: Act 2019-9 requires electronic invoices for certain online sales with VAT collected at checkout.
B2G e-invoicing in Barbados
B2G e-invoicing is not mandatory, and no portal for invoices to public bodies has been identified. Under section 28A, inserted by Act 2015-33, the government accounting officer pays a contract's VAT to the BRA, not the supplier.
B2B e-invoicing in Barbados
No general structured B2B e-invoicing mandate applies. Act 2017-18 sets thresholds of BBD 200,000 over 12 months or BBD 16,667 monthly for businesses operating under 12 months, including associates’ supplies but excluding capital-goods sales.
Registrants must issue tax invoices to other registrants within 30 days of the supply (section 7(7)). Each shows the words "tax invoice", a sequential number, issue date, supplier name, address and registration number, recipient name and address, description and quantity, consideration, VAT rate and tax per category, total tax and total payable.
- Register with the BRA, note your taxable periods and set up TAMIS.
- Configure the particulars and 30-day window in your ERP or billing system.
- Test one period of invoices against your VAT return.
Cross-border rules:
- Imports: import VAT, paid at customs entry (section 7(3)), counts as input tax (section 43).
- Exports: goods exported under customs law, with the required certificates, are zero-rated.
- Services: certain services to non-residents, paid in foreign currency, are zero-rated (First Schedule).
B2C e-invoicing in Barbados
There is no general B2C e-invoicing mandate, and no fiscal device or fiscalization regime has been identified. Registrants must give consumers a receipt for supplies of $20 or more (section 9), showing seller name and registration number, a sequential number, date, total, and VAT rate and tax.
Buyer details are not required, and no POS certification is prescribed. For certain online sales with VAT collected at checkout, Act 2019-9 requires an electronic invoice at payment.
E-reporting and VAT compliance
Barbados has periodic e-reporting of invoice data. VAT returns are filed in TAMIS for taxable periods of generally two months, with filing and payment due within 21 days after the end of each taxable period.
VAT rates are 17.5% standard, 22% for telecommunications, 7.5% for hotels and qualifying tourism, 10% for approved rental car companies from October 1, 2026, and 0% for zero-rated items.
- Corrections: a credit or debit note is required when a supply is cancelled, returned or repriced, or shows the wrong VAT (section 52). It cites the original invoice number, date and VAT; the supplier adjusts output tax, and a registered buyer adjusts input tax claimed.
- Reconciliation: regulation 7 requires a periodic summary statement reconciling sales, purchases, input tax and credit notes to net VAT.
- Retention: keep records 7 years after the end of the year they relate to, longer for open objections, appeals or BRA demands (section 75). Store them in Barbados, retrievable for the BRA, with compliant archiving.
Penalties for non-compliance
Penalties under the VAT Act, Cap. 87 start at $100, and evasion fines reach the greater of $25,000 or 200% of the tax evaded.
Offence | Penalty (BBD) |
|---|---|
Late VAT return | $100 |
Late VAT payment | 10% of unpaid tax, plus 1% interest per month |
No tax invoice, credit note or debit note | Up to $1,000 |
Failure to register | Up to $1,000 and lost input tax refunds |
No consumer receipt for $20 or more | $5,000, one year in prison, or both |
Inadequate records | $1,000 to $5,000 |
Knowingly issuing a false tax invoice | $5,000, six months in prison, or both |
Other breaches with no set fine | $25,000 |
Your trusted partner for e-invoicing
Barbados has no general e-invoicing mandate, but VAT registrants must issue tax invoices within 30 days of the supply. DDD Invoices gives you one API to issue, receive and archive compliant invoices across every country we support, so your ERP or billing software connects once and we keep each country's format, validation and deadline rules up to date. Barbados is not yet on our country coverage list, and talking to us is the fastest way to add it to the roadmap.
{{__CTA:TalkToUsCta__}}
FAQs
What are the e-invoicing requirements in Barbados?
Barbados has no general e-invoicing mandate for B2B, B2C or B2G transactions as of October 2026. VAT registrants must still issue tax invoices to other registrants within 30 days of the supply.
Why do Barbados buyers need a valid tax invoice?
Except for import VAT, input tax can only be claimed with a tax invoice from another registrant. The invoice must show the words "tax invoice", a sequential number, VAT rate, tax amount and totals.
When are VAT returns due in Barbados?
VAT returns and payments are due within 21 days after the end of each taxable period. Taxable periods are generally two months, assigned by the BRA, and returns are filed online through TAMIS.
How long must businesses keep VAT records in Barbados?
Businesses must keep VAT records for 7 years after the end of the year they relate to. Electronic records must stay retrievable, and open objections or appeals extend the period, so plan compliant invoice archiving.