
E-Invoicing in Grenada
Author
Shamyudha

Grenada imports most of what it consumes, so VAT on imports and tourism carries much of the tax base. G-TAX took filing online in 2024, yet e-invoicing in Grenada remains a paper or PDF exercise overseen by the Inland Revenue Division.
Businesses with taxable supplies of EC$300,000 or more in 12 months must register for VAT and issue VAT invoices to registered customers, or sales receipts to others. There is no structured e-invoicing mandate, clearance platform or confirmed start date. Returns and payment are due within 20 days after each monthly tax period.
Latest news
Embeds a monitoring pages group for this blog article
{{__MONITORING_PAGES_GROUP:blog_articles_603__}}On January 26, 2024, the Inland Revenue Division (IRD), a division of the Ministry of Finance, launched G-TAX for online VAT, PAYE and corporate income tax filing and payment.
No general nationwide structured e-invoicing mandate has been identified. G-TAX supports tax registration, filing, payment and account management.
{{__CTA:IntegrationStepsCta__}}
Is e-invoicing mandatory in Grenada?
E-invoicing is the exchange of invoices in a structured format that software can process without re-entry.
Grenada has not adopted it: the Value Added Tax Act, Cap. 333. A prescribes invoice content, not format, so PDF, paper and structured files are equally valid under its post-audit model.
Grenada VAT and digital tax timeline
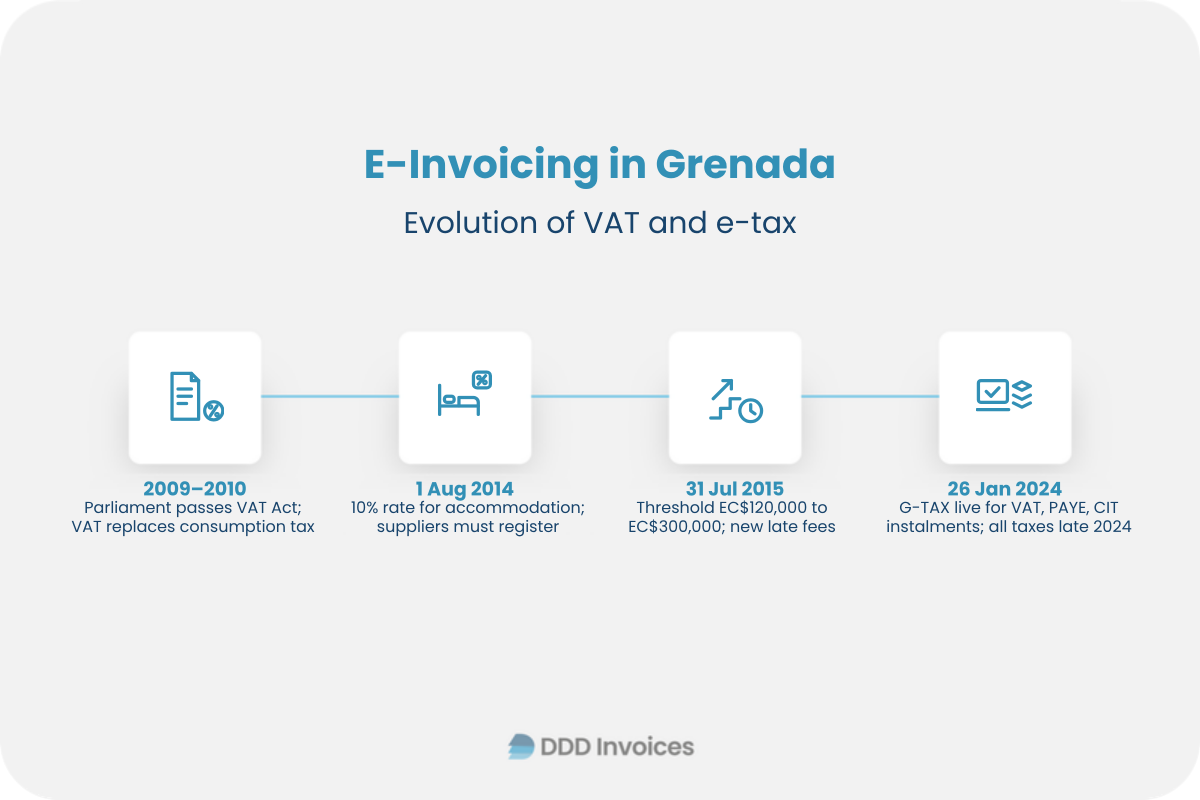
- 2009 to 2010: Parliament passes the Value Added Tax Act (Act No. 23 of 2009); VAT replaces the General Consumption Tax, per the VAT overview.
- August 1, 2014: Act No. 18 of 2014 sets a 10% rate for accommodation and requires accommodation suppliers to register.
- July 31, 2015: Act No. 21 of 2015 raises the registration threshold from EC$120,000 to EC$300,000 and reworks late-filing fees.
- January 26, 2024: G-TAX goes live for VAT, PAYE and CIT instalments, extended to all tax types in late 2024.
B2G e-invoicing in Grenada
There is no B2G e-invoicing mandate. Public bodies buy under the same VAT rules: a VAT invoice if registered, otherwise a sales receipt. No Peppol or XML format applies, so suppliers using a unified e-invoicing API elsewhere simply render a compliant PDF.
B2B e-invoicing in Grenada
B2B e-invoicing is voluntary. Section 37 of the VAT Act requires an original VAT invoice to each registered recipient at the time of supply; a sales receipt may replace it only for cash supplies of EC$50 or less.
The Ministry of Finance VAT documents guidance lists the particulars: the words “VAT Invoice”, both parties’ names, addresses and TINs, a serial number, issue and supply dates, a description, the consideration and the VAT charged. Under section 39, overcharged VAT is corrected with a VAT credit note and undercharged VAT with a VAT debit note, each citing the reason, the original consideration and the VAT difference.
- Register once taxable supplies reach EC$300,000 in any 12 months and obtain the TIN.
- Configure templates with every particular and sequential numbering in your ERP integration.
- Link credit and debit notes to the original invoice number.
- Archive issued and received documents chronologically, for example via e-invoice archiving.
Import VAT is paid at the border, with the customs entry supporting the input credit. Exports are zero-rated under the First and Second Schedules if export evidence is kept. Imported services from non-residents carry a section 22 reverse charge when the buyer lacks full input credit.
B2C e-invoicing in Grenada
Consumer sales need a sales receipt under section 38, labelled “VAT Sales Receipt”, with the supplier’s name, address and TIN, date, description, total and VAT. Supplies of EC$5 or less are exempt.
Grenada has no fiscal device, certified POS or receipt reporting rules, including for online sellers. A POS integration needs no local certification; our fiscalization platform covers countries that do.
E-reporting and VAT compliance
Grenada has periodic e-reporting. VAT applies at 15%, with 10% for hotel or holiday accommodation and dive packages, and 0% for zero-rated supplies, under section 8 of the VAT Act.
Returns and payment are due within 20 days after the end of the monthly tax period, as the IRD’s monthly due-date notices confirm. The return reconciles output tax, input credits backed by valid invoices or customs documents, and adjustments. Records stay in Grenada for seven years under section 110: invoices, adjustment notes, customs documents and reverse-charge evidence, on paper or in accessible electronic form.
Penalties for non-compliance
Fines run from fixed penalties of EC$2,500 to court fines of EC$30,000 under Part XIV and the Sixth Schedule of the VAT Act, amended by Act No. 21 of 2015.
Offence | Fine |
|---|---|
Late VAT return (s. 44) | Greater of EC$500 or 5% of tax due plus 1% per month, capped at EC$10,000 |
Late VAT payment (s. 46) | 20% of the unpaid VAT, plus interest |
False or missing VAT invoice, note or receipt (s. 78) | Up to EC$25,000 or 3 years’ imprisonment |
Failure to file a return (s. 79) | Up to EC$20,000 or 3 years’ imprisonment |
Failure to keep records (s. 81) | Fixed penalty EC$2,500; on conviction up to EC$5,000 |
Your trusted partner for e-invoicing
Grenada asks for correct VAT invoices, sales receipts and seven-year archives rather than structured e-invoices, but most companies trading here also sell into markets where clearance and e-reporting are already law.
DDD Invoices gives you one API to issue, receive and archive compliant invoices across every country we support, so your ERP or billing software connects once and we keep each country's format, validation and deadline rules up to date for you. Grenada is on our country coverage list as collecting interest, and talking to us is the fastest way to move it up the roadmap.
{{__CTA:TalkToUsCta__}}
FAQs
Is e-invoicing mandatory in Grenada?
No, Grenada has no e-invoicing mandate and no government platform that clears or receives invoices. Registered suppliers must issue VAT invoices with the prescribed particulars, in paper or electronic form, under the VAT Act.
What must a VAT invoice in Grenada contain?
A VAT invoice must show the words “VAT Invoice”, both parties’ names, addresses and TINs, a serial number and dates. It must also describe the supply and state the consideration and the VAT charged separately.
When are VAT returns due in Grenada?
VAT returns and payment are generally due by the 20th of the following month. Applicable deadline adjustments or IRD extensions may change the due date.
How does G-TAX relate to e-invoicing in Grenada?
G-TAX is the IRD’s online system for tax registration, filing and payment, launched in January 2024. It does not issue, validate or transmit invoices, so invoicing stays with the supplier’s own documented software.