
E-Invoicing in the Philippines: BIR EIS Requirements
Author
Shamyudha
In 2024, the invoice became the main proof of a Philippine sale, and the Bureau of Internal Revenue (BIR) is digitizing it. E-invoicing in the Philippines centers on its Electronic Invoicing/Receipting System (EIS).
Large taxpayers, e-commerce sellers above micro size and users of computerized accounting or invoicing software must e-invoice by December 31, 2026. Each needs a Permit to Issue (PTI), then EIS Certification within six months. Micro taxpayers are exempt; sales reporting awaits separate rules.
Latest news
Posted on October 22, 2026, RMC 112-2026 sets transition rules for RR 6-2026, which adds creditable withholding tax (CWT) to invoices. From January 1, 2027, covered e-invoicing systems must show a CWT field on every invoice, even when no CWT applies.
Under RMC 110-2026 of October 12, 2026, e-invoicing service providers need BIR accreditation before going live, so check your vendor's certificate. Your PTI duties remain.
{{__CTA:IntegrationStepsCta__}}
What is e-invoicing and why has the Philippines adopted it?
E-invoicing is issuing invoices as structured data that software reads without manual entry.
The BIR wants data it can extract automatically, so RR 11-2025 rules out scanned paper invoices. Taxpayers that also report sales electronically get an extra one-time deduction on setup costs. There is no clearance step: sellers invoice buyers directly.
The evolution of e-invoicing in the Philippines
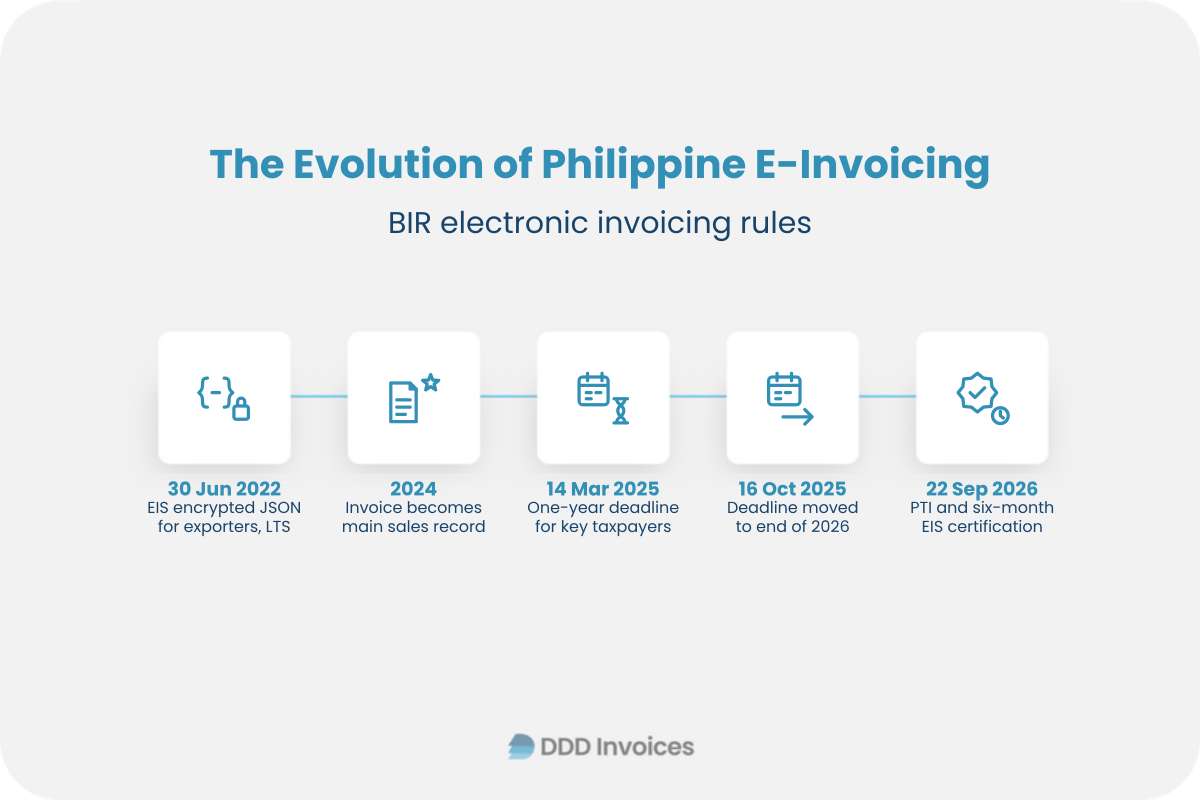
- June 30, 2022: RR 8-2022 applies the TRAIN Law through the EIS, using encrypted JSON, for exporters, e-commerce and Large Taxpayers Service (LTS) taxpayers.
- 2024: the Ease of Paying Taxes Act (EOPT, RA 11976) makes the invoice the main sales document. The CREATE MORE Act (RA 12066) updates Sections 237 and 237-A.
- March 14, 2025: RR 11-2025 takes effect with a one-year deadline for e-commerce, LTS and EOPT large taxpayers.
- October 16, 2025: RR 26-2025 moves the deadline to December 31, 2026 for all four covered groups.
- September 22, 2026: RMC 98-2026 adds the PTI and a six-month EIS Certification window.
B2G e-invoicing in the Philippines
Unlike countries with mandatory B2G e-invoicing, the Philippines has no separate B2G mandate, portal or date. Covered sellers e-invoice agencies like any customer; e-invoices must be verifiable electronically or manually as the BIR prescribes.
B2B e-invoicing in the Philippines
B2B e-invoicing is mandatory by December 31, 2026 under RR 26-2025 for four groups:
- E-commerce sellers classified as small, medium or large.
- LTS taxpayers.
- EOPT large taxpayers, with gross sales of PHP 1 billion or more under RR 8-2024.
- Users of a computerized accounting system (CAS), computerized books of accounts (CBA) with e-invoicing, or other invoicing software.
Micro taxpayers, under PHP 3 million in gross sales, are exempt. Exporters and registered business enterprises (RBEs) outside that last group, and POS users, join under a later RR.
Since the EOPT Act, the invoice is the sole principal sales document; official receipts are supplementary. RR 7-2024 requires the seller's name, VAT or non-VAT TIN, address, "Invoice", date and serial number. It also lists buyer details, quantity, unit cost, description, total and separate VAT. RR 6-2026 adds any CWT.
- Get a PTI: apply at your Revenue District Office (RDO) or Large Taxpayer Office, covering all branches. RMC 98-2026 sets a 20-working-day review of complete applications.
- Certify: pass EIS Certification, five tests or seven with API callback, within six months of the PTI.
- Plan for downtime: use BIR-authorized manual invoices in outages, then replace them with e-invoices quoting their numbers.
B2C e-invoicing in the Philippines
Covered groups e-invoice consumer sales too. VAT-registered sellers invoice every sale; others invoice sales of PHP 500 or more, or any sale on request, under the EOPT Act. B2C invoices need no buyer address or TIN, and may be printed when electronic delivery is impractical.
POS systems lacking electronic issuance and reporting produce no e-invoices.
E-reporting and VAT compliance in the Philippines
Electronic sales reporting is not yet mandatory for covered groups; it awaits separate BIR rules and a Permit to Transmit (PTT).
VAT is 12% under Sections 106 and 108 of the Tax Code, and exports are zero-rated. VAT taxpayers file BIR Form 2550Q within 25 days after each quarter. Nonresident digital services carry 12% VAT under RA 12023 and RR 3-2025, reverse-charged by VAT-registered buyers.
Reduce amounts with a credit note citing the original e-invoice, increase them with a new e-invoice, and never delete or alter one. Keep records in compliance-ready storage for five years from the day after the return deadline, as RR 7-2024 explains under Section 235.
Penalties for non-compliance in the Philippines
Fines start at PHP 1,000 under Section 264 of the Tax Code; Sections 264-A and 115 add daily penalties and closure.
Offence | Fine |
|---|---|
No invoice, or one missing required information (Section 264(a)) | PHP 1,000 to PHP 50,000 and 2 to 4 years' imprisonment |
VAT-registered seller not issuing invoices (Section 115) | Business closure for at least 5 days |
Not transmitting sales data once required (Section 264-A) | Higher of PHP 10,000 or 0.1% of annual net income daily; permanent closure past 180 days a year |
Your trusted partner for e-invoicing in the Philippines
Covered taxpayers need structured data, a PTI and a tested system, as e-invoicing is mandatory by December 31, 2026. DDD Invoices validates data and offers a sandbox through one unified e-invoicing API, letting your ERP issue, receive and archive invoices in 30+ countries. Our country coverage list shows the Philippines as collecting interest, so share your timeline and we can plan together.
{{__CTA:TalkToUsCta__}}
FAQs
When is the Philippine e-invoicing deadline?
Covered taxpayers must issue e-invoices on or before December 31, 2026, under RR 26-2025 and RMC 98-2026. The Commissioner may extend that date, but no further extension had been issued by November 3, 2026.
What counts as a BIR e-invoice?
An e-invoice is structured data from a BIR-registered system, sent to the buyer electronically and ready for reporting. Scanned paper invoices and invoices typed in Word, Excel or Google Sheets never count as e-invoices.
Why isn't EIS sales reporting mandatory yet?
Sales reporting under Section 237-A is a separate duty that starts only after the BIR issues implementing rules. Until then, covered taxpayers issue e-invoices and must still pass EIS Certification within six months of the PTI.
How do you correct a Philippine e-invoice?
Issue a separate document that references the original, because an issued e-invoice cannot be deleted or altered. Use a credit note to reduce the invoiced amount, or a new e-invoice to increase it.