
E-Invoicing in Trinidad and Tobago: Current Status and VAT Invoice Requirements

Trinidad and Tobago has no announced national e-invoicing mandate as of 28 October 2026, and no format or clearance model has been published. Invoice duties sit in the VAT legislation, administered by the Inland Revenue Division (IRD).
These rules set the wording and fields of a tax invoice, not a government e-invoice format or clearance platform. The IRD offers online taxpayer services, but none is presented as invoice clearance or mandatory electronic invoicing.
Latest News
Embeds a monitoring pages group for this blog article
{{__MONITORING_PAGES_GROUP:blog_articles_609__}}The TTRA is a planned semi-autonomous body that merges the IRD and Customs and Excise.
Is E-Invoicing Mandatory in Trinidad and Tobago?
Trinidad and Tobago has not published an e-invoicing system. Businesses follow the standard VAT invoice rules set out by the IRD. The IRD is a division of the Ministry of Finance and the principal tax collecting agency.
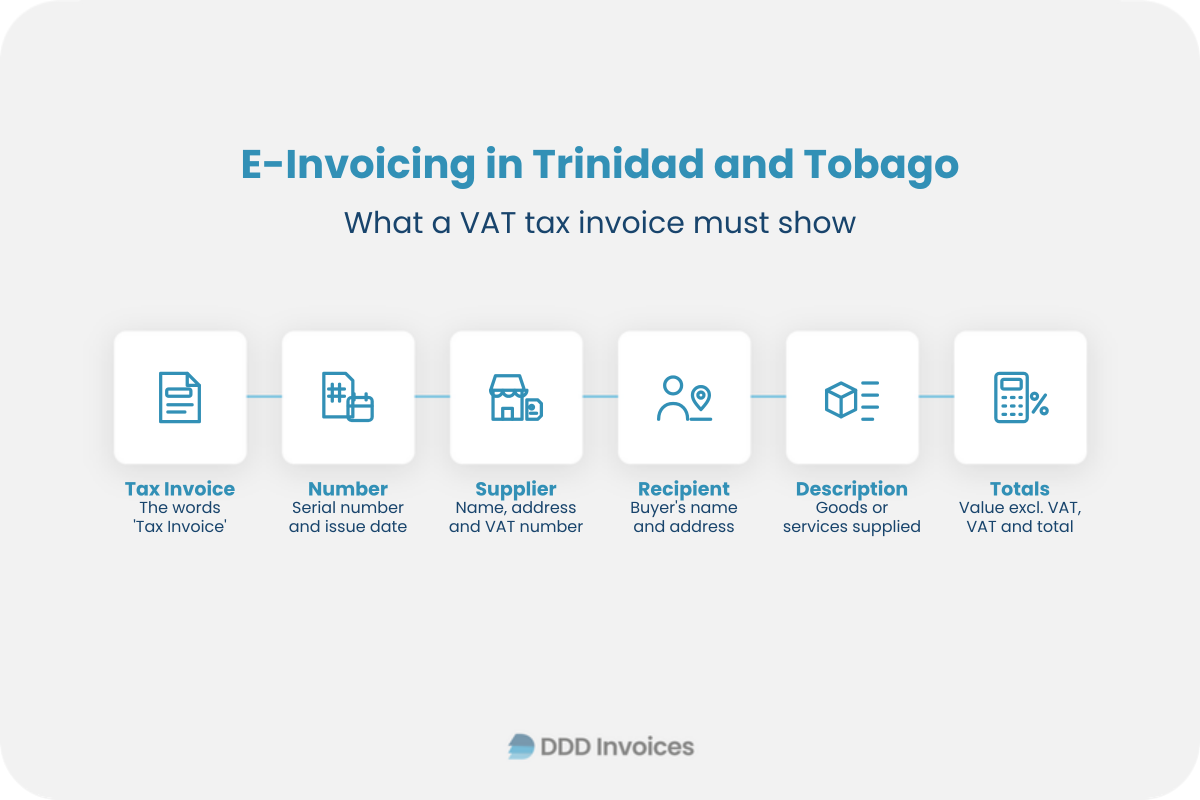
Every VAT-registered business must issue a tax invoice. It must show:
- the words "Tax Invoice"
- a serial number and the date of issue
- the supplier's name, address and VAT registration number
- the recipient's name and address
- a description of the goods or services
- the VAT-exclusive value, the VAT amount and the total
E-Invoicing Timeline
Planned: The TTRA is set up by legislation passed in 2021, as a merger of the IRD and Customs and Excise.
2026: No e-invoicing implementation date, pilot or format has been published.
B2G E-Invoicing in Trinidad and Tobago
B2G e-invoicing does not exist in Trinidad and Tobago. Suppliers to government bodies issue standard VAT tax invoices. The contract or tender sets the purchase-order, delivery and payment terms. The government body is the buyer, so its name and address should appear as the recipient.
B2B E-Invoicing in Trinidad and Tobago
B2B e-invoicing is not mandatory. Businesses may send invoices by email or accounting software by agreement, which is a voluntary commercial practice. The compliance point is a correct tax invoice, including the buyer's details.
B2C E-Invoicing in Trinidad and Tobago
B2C e-invoicing does not exist in Trinidad and Tobago. Retailers do not have to use fiscal devices or issue e-receipts, and they don't report sales to the IRD in real time. VAT-registered businesses must still issue a tax invoice for taxable sales when required, subject to the exemption for fast food outlets, gas stations and cinemas above.
E-Reporting and Tax Compliance
Trinidad and Tobago does have periodic reporting, in the form of VAT returns filed through the IRD's tax administration channels. These are summary returns, not lists of individual invoices.
A VAT-registered business files a return for each tax period. The return is due by the 25th day of the month following the end of the tax period. Payment is due with the return. The return reports summary figures for the period, not individual invoices. Invoices need not be attached to the return, but they must meet the invoicing requirements for all claims and be provided to the IRD on request.
Records, including tax invoices, are kept in English, in the currency of Trinidad and Tobago and at the principal place of business. The retention period is six years, or three years from the date of filing returns, whichever is later.
Penalties for Non-Compliance
Trinidad and Tobago has no e-invoicing penalty. Failures on VAT invoices, records or returns fall under the general VAT penalties.
How DDD Invoices Supports Compliance?
Businesses in Trinidad and Tobago need accurate tax invoices, consistent numbering and a secure archive, even without an e-invoicing mandate.
DDD Invoices is an API-first platform that lets business software issue, receive, archive and manage locally compliant invoices through one integration. It can centralise billing data, manage corrections and credit notes, and retain audit-ready records. Trinidad and Tobago support is pending, so check any setup against current IRD guidance.
{{__CTA:TalkToUsCta__}}
FAQs
Who must issue e-invoices in Trinidad and Tobago?
No one. No national e-invoicing mandate has been announced.
What is the IRD’s e-Tax service?
It is a taxpayer administration portal run by the Inland Revenue Division (IRD). It is not an invoice platform, so Trinidad and Tobago has no e-invoicing portal.
How long must records be kept?
Six years, or three years from the date of filing returns, whichever is later, according to the IRD’s VAT page.
Which format is required, such as Peppol or XML?
None. No e-invoicing format has been published.
When might this change?
No date has been announced. Check the IRD and TTRA websites for updates.