
Fiscalization and Real-Time Reporting in Mayotte (2026)
Author
Shuaa

Fiscalization in Mayotte differs from mainland France’s VAT-based cash-register regime. Under Article 294 of the French General Tax Code, VAT is provisionally not applicable in Mayotte. Official tax guidance also expressly excludes the territory from the corresponding cash-register certification-control procedure.
As of October 2026, businesses conducting local sales in Mayotte are not subject to fiscalization through certified POS software under that VAT-based framework. They must instead maintain sales records and supporting documents according to their accounting and tax regime. The framework does not establish a Mayotte implementation deadline, mandatory fiscal receipt format or real-time transmission requirement for local retail transactions.
Latest News
Embeds a monitoring pages group for this blog article
{{__MONITORING_PAGES_GROUP:blog_articles_573__}}- February 2026 — France restored publisher compliance attestations, cancelling the September 2026 third-party certification requirement. Mayotte remains excluded from the corresponding POS certification controls.
- March 2026 — Updated tax guidance confirms Mayotte remains excluded from cash-register certification controls because VAT is provisionally not applicable there.
What Does ‘Fiscalization’ Mean in Mayotte?
Mayotte’s existing requirements center on accounting and sales documentation rather than France’s VAT-based certified cash-register system. Merchants must record business transactions chronologically and retain accounting documents and supporting evidence, even though Mayotte’s VAT position excludes the territory from the corresponding cash-register certification-control procedure.
This exclusion is territorial, not simply a small-business exemption. Businesses operating in both Mayotte and mainland France should therefore assess their mainland operations separately rather than assume Mayotte’s exclusion applies company wide.
Timeline
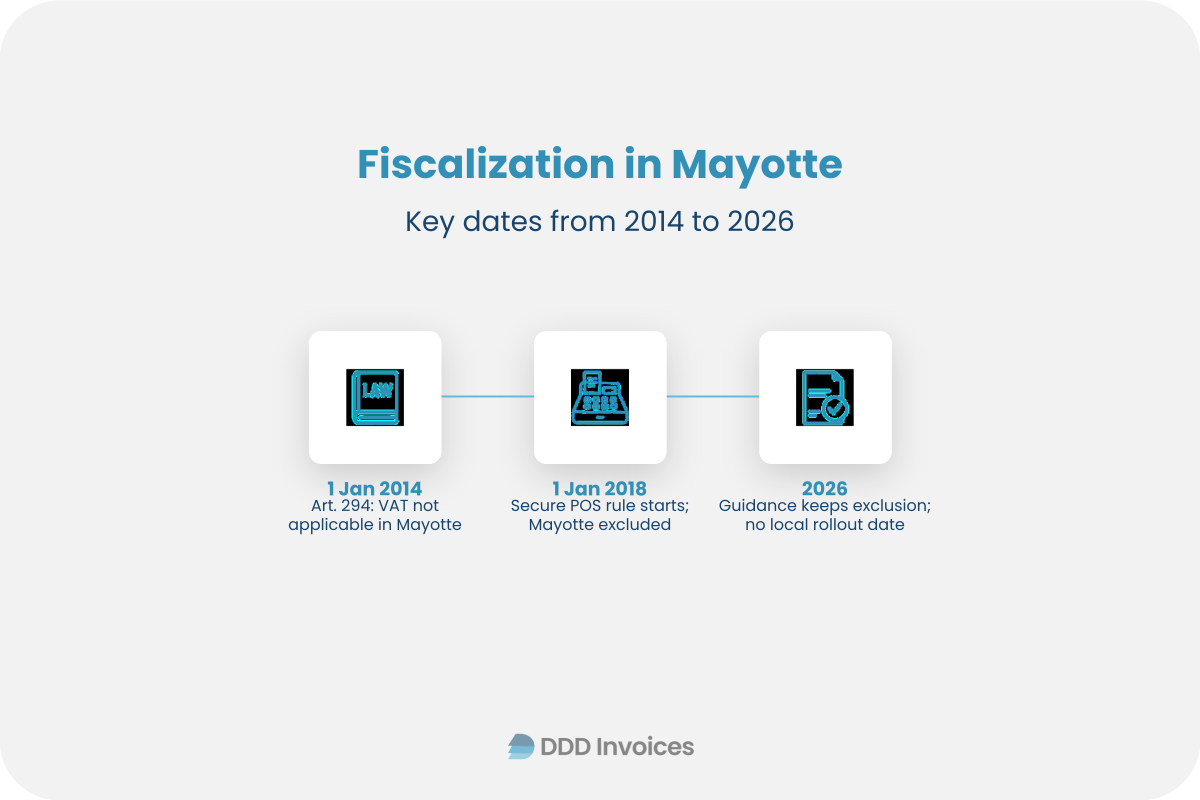
- 2014 — Article 294’s current wording took effect on 1 January, expressly stating that VAT is provisionally not applicable in Mayotte. This is a VAT-treatment date, not the introduction of fiscalization.
- 2018 — France’s secure cash-register software requirement began on 1 January for businesses within its VAT-based scope. Mayotte was excluded from the corresponding territorial control procedure.
- 2026 — Updated guidance maintains Mayotte’s exclusion without introducing a local fiscalization rollout date.
Who Does Fiscalization in Mayotte Affect?
Mayotte fiscalization requirements should be distinguished from the accounting obligations affecting local businesses.
Retailers, restaurants and other merchants conducting local sales are not required to obtain VAT-based POS certification merely because they accept cash, serve consumers or use cash-register software. Official guidance excludes Mayotte from the corresponding certification-control procedure because VAT is provisionally not applicable there.
However, individuals and legal entities with merchant status must record movements affecting their business assets chronologically under Article L123-12 of the Commercial Code. This general accounting obligation does not distinguish between consumer and business customers.
Fiscal Regulations That Will Affect Businesses in Mayotte
Cash Register and POS Requirements
France’s VAT-based anti-fraud cash-register framework does not impose certified POS software on Mayotte’s local sales. Official guidance excludes Mayotte from the corresponding certification-control procedure because VAT is provisionally not applicable there. Businesses should therefore not treat mainland certification rules or deadlines as Mayotte cash register requirements.
The absence of that certification obligation does not remove merchants’ responsibilities to maintain accounting records and retain supporting documentation.
Sales Recording
Merchants must record movements affecting their business assets chronologically. Under the general accounting rules, each entry must identify its origin, content and accounting allocation, together with references to the supporting document. These are accounting obligations, not requirements to use certified POS software.
Real-Time Reporting
The cash-register control procedure described in BOFiP concerns checking software compliance certificates or attestations, not automatically transmitting each retail sale. Mayotte is expressly excluded from that procedure.
Businesses nevertheless remain subject to ordinary tax-control requests for information and supporting evidence. Mayotte’s exclusion from POS certification controls should not be confused with exemption from those responsibilities.
Record Retention and Auditability
Under Article L123-22 of the Commercial Code, accounting documents and supporting evidence must be retained for ten years. Accounting records relating to transactions and inventory must be maintained without blanks or alterations. These safeguards are separate from fiscal-device certification.
Article L102 B of the Tax Procedures Code generally requires documents subject to tax-control rights to be retained for six years, calculated from the last recorded transaction or the date the document was established. Records created or received electronically must remain in electronic form during that period. Where both rules apply, the six-year tax retention period does not replace the ten-year commercial accounting obligation.
What Are the Implications and Penalties of Non-Compliance in Mayotte?
Mayotte is excluded from France’s VAT-based cash-register certification-control procedure. The associated certification penalties should therefore not be presented as penalties for Mayotte businesses simply using uncertified software for local sales.
General document-compliance sanctions remain relevant. Article 1734 of the French General Tax Code provides a €10,000 fine per request for refusing or obstructing the communication of documents or information requested under the tax administration’s right of communication. A fine of the same amount applies where the relevant documents have not been maintained or have been destroyed before the prescribed retention period expires. This is a document-compliance sanction, not a Mayotte real-time reporting penalty.
Your Trusted Partner for Fiscalization in Mayotte
Planning a POS or retail software integration in Mayotte starts with understanding its distinct regulatory position. Your priority should be reliable sales recording, secure document retention and accessible records for audits, not applying mainland France’s VAT-based POS certification requirements to local sales.
Make that distinction central to your integration planning. Discuss your transaction-recording workflows and technical needs with DDD Invoices to explore an approach suited to your business, while assessing any operations outside Mayotte separately.
Displays a content card with title, subtitle, list/body, and action button
{{__CTA:GenericCtaJson:{"type":"content","contentCta":{"layout":"cardList","title":"Talk to us!","subtitleHtml":"Still have questions?","button":{"href":"https://calendly.com/ddd-invoices/30min-intro","label":"Book a free 30min call","color":"white"},"bodyHtml":"In the <strong>30min free call</strong> we will discuss:","listHtml":"<ul><li><strong>your requirements</strong> in invoicing</li><li>how integration works</li><li><strong>demo</strong> of the product</li><li>next steps</li></ul>"}}__}}FAQs
Is fiscalization mandatory in Mayotte?
Mayotte’s local sales are excluded from France’s VAT-based cash-register framework, with official guidance expressly excluding Mayotte from the corresponding certification-control procedure. Applicable accounting, sales-recording and document-retention obligations still apply.
Do businesses need certified POS systems in Mayotte?
Not under the French VAT-based cash-register framework for local sales. Official guidance expressly excludes Mayotte from its corresponding certification-control procedure because VAT is provisionally not applicable there.
Is real-time transaction reporting required in Mayotte?
The VAT-based procedure discussed here concerns checking software certificates or attestations, not transmitting each retail transaction, and Mayotte is excluded from it. Businesses must nevertheless retain records subject to tax-control rights.
How long must businesses retain sales records?
Accounting documents and supporting evidence must be retained for ten years under Article L123-22. A separate six-year rule under Article L102 B applies to documents subject to tax-control rights, including preservation in electronic form for records created or received electronically. Where both apply, the six-year rule does not shorten the ten-year obligation.